


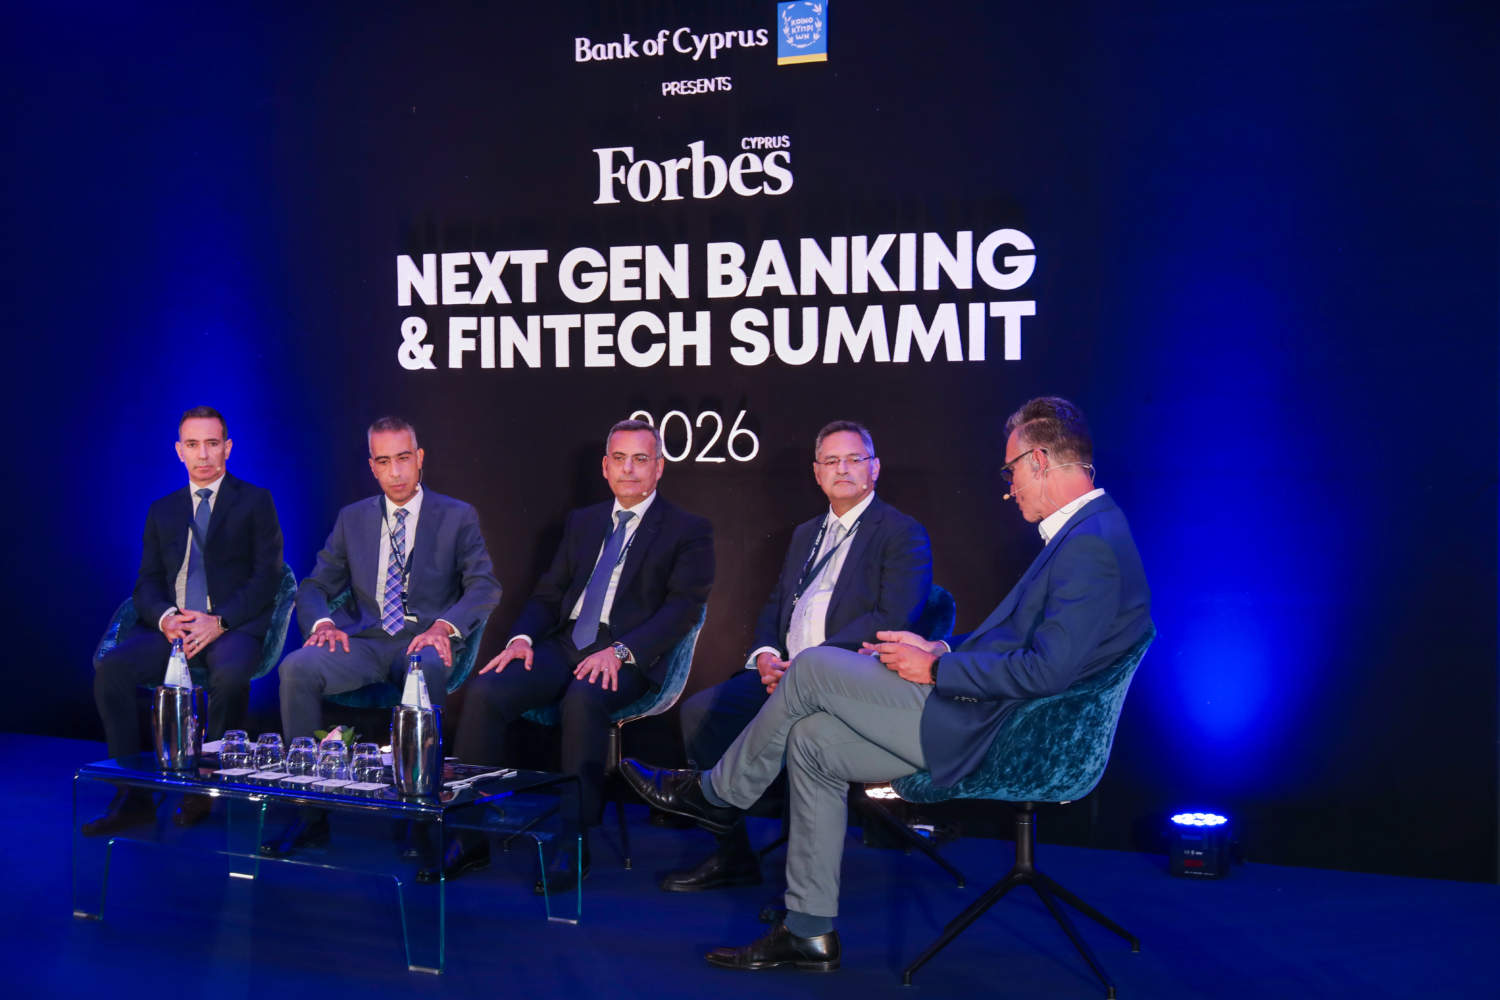
Regulatory certainty, a resilient banking system and more efficient public services are essential if Cyprus is to strengthen its position as an international financial technology centre, senior regulators and government officials told the Forbes Cyprus Next Gen Banking & Fintech Summit on Tuesday.
The discussion, held at the Four Seasons Hotel in Limassol, brought together Central Bank Governor Christodoulos Patsalides, Cyprus Securities and Exchange Commission (CySEC) Chairman George Karatzias, Deputy Minister of Research, Innovation and Digital Policy Nicodemos Damianou and Invest Cyprus Chairman Evgenios Evgeniou.
Moderated by Demetrios Zoppos, partner at 33East, the panel examined how Cyprus could compete with other financial centres while maintaining strong supervision and attracting businesses, investment and specialised talent.
Evgeniou argued that effective regulation should be viewed as an advantage rather than an obstacle to attracting financial technology companies.
“Regulation is not an impediment to growth and to competitiveness. What is an impediment to growth and competitiveness is uncertainty,” he said.
He stressed that companies need clear regulatory requirements, timely responses and opportunities to test innovative financial products before expanding into European markets.
Banks in stronger position than in 2013
Patsalides highlighted the transformation of Cyprus’s banking system since the 2013 financial crisis, pointing to stronger capital ratios, ample liquidity, profitability and improved asset quality.
“Banking is all about trust,” the Central Bank Governor said, emphasising that the sector had substantially strengthened its ability to withstand external shocks.
He said Cypriot banks now had some of the strongest capital positions in the European Union, with sufficient liquidity to support lending to households and businesses.
The banking sector’s governance had also improved, he added, giving institutions greater capacity to respond to economic uncertainty while financing business growth.
Turning to financial supervision, Karatzias said Cyprus had strengthened its regulatory credibility through a more targeted, risk-based approach.
CySEC had concentrated resources on higher-risk business models, cross-border marketing practices and governance shortcomings, taking enforcement action where necessary, including fines, licence suspensions and revocations.
He stressed the importance of cooperation with European supervisory authorities and of providing businesses with timely regulatory guidance without compromising oversight.
Investors want talent and efficient government
Damianou said international technology companies considering Cyprus increasingly focused on the availability of qualified professionals and the country’s long-term development strategy.
Access to engineering and artificial intelligence specialists was particularly important, alongside policies allowing companies to recruit and relocate international talent.
He described the government’s objective as moving Cyprus beyond a predominantly services-based economy towards a model driven increasingly by knowledge, innovation and technology.
However, he acknowledged that attracting businesses also depended on making public administration more efficient.
Damianou outlined efforts to modernise government systems, including social insurance, education, public services and company registration.
According to the Deputy Minister, newly introduced digital government services covering areas such as civil registration, social welfare, social insurance and military service had been used more than 250,000 times over the preceding 12 to 18 months.
Nevertheless, he cautioned that technology alone could not solve administrative inefficiencies.
“Digitisation alone is not going to cut through bureaucracy and get rid of it,” Damianou said, arguing that government procedures themselves needed to be simplified.
He also referred to the Business Support Centre, which coordinates assistance for companies establishing operations in Cyprus, and said improvements to company registration systems were being developed.
Fintech investment and the importance of trust
Evgeniou said efforts to attract international companies and specialised professionals had contributed to economic growth, job creation and diversification.
The broader technology sector now accounted for approximately 14% to 15% of Cyprus’s GDP, depending on the calculation method, he said.
He stressed that Cyprus wanted businesses that established a genuine local presence, recruited employees and developed operations rather than merely using the country as a registration base.
In some cases, he said, companies had completed their relocation and establishment in Cyprus within five weeks of deciding to move, excluding regulatory authorisations.
The discussion also covered the role of regulatory innovation initiatives, including CySEC’s regulatory sandbox and the Central Bank’s Innovation Hub.
Patsalides said the Central Bank had introduced a pre-application process allowing prospective financial institutions to discuss regulatory expectations before submitting formal applications.
“Speed is important, but quality is even more important,” he said, emphasising the need to protect the long-term credibility of Cyprus’s financial services sector.
Looking towards 2030, the panellists identified institutional trust, regulatory certainty and the ability to retain and grow internationally competitive businesses as important measures of Cyprus’s success.
Read more:

