


Many businesses still treat insurance as a routine obligation or an annual purchase, rather than as part of their overall risk management. As a result, they may hold several policies yet remain exposed to risks that could cause serious financial loss or operational disruption.
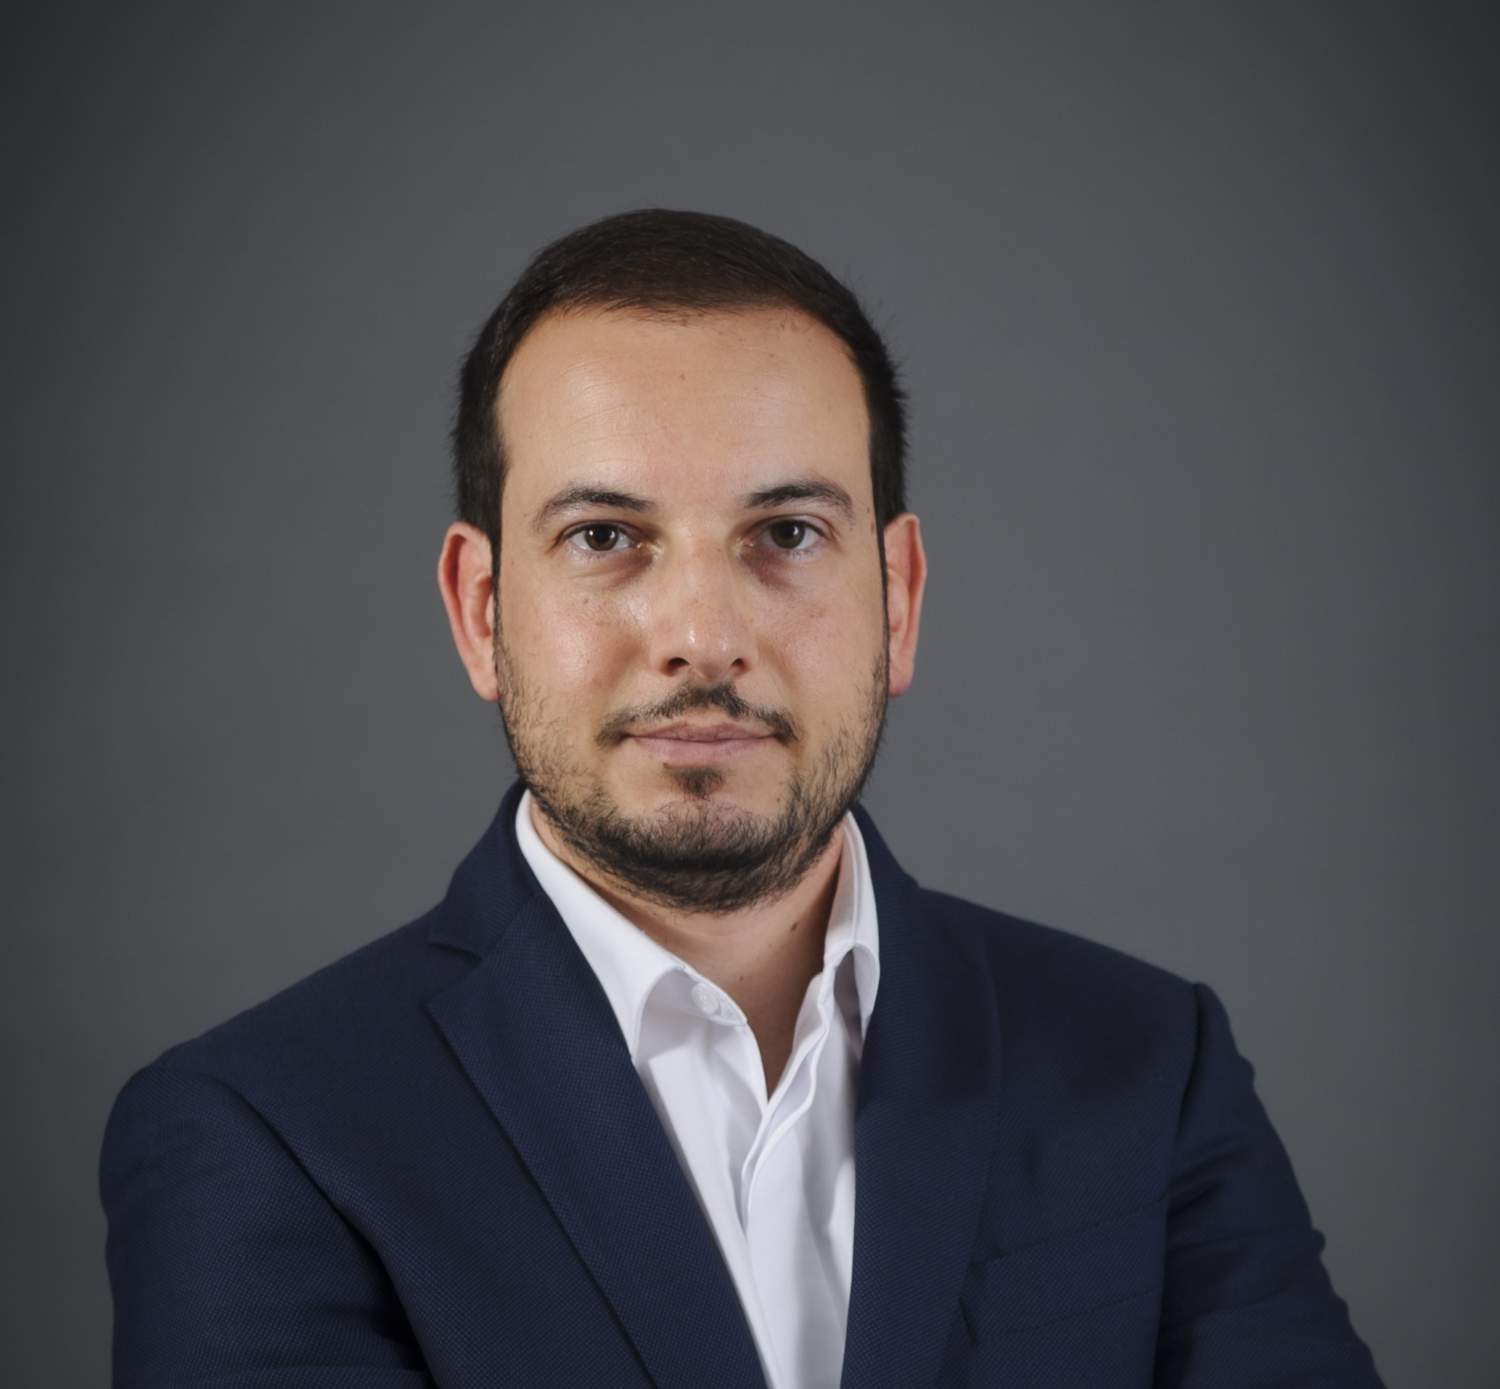
An interview with Andreas Hadjisofocleous, Managing Director of HJS Insurance Agents & Consultants
How do you assess the current state of the insurance market in Cyprus, and where does your company fit within it?
The insurance market in Cyprus is mature, competitive and undergoing significant transformation. Clients are now better informed and seek transparency, speed, expertise and solutions tailored to their actual needs. At the same time, businesses are becoming more complex and international in scope, so many risks cannot be addressed effectively through standard insurance products alone.
HJS Insurance operates as a specialist insurance intermediary with a strong emphasis on advice and a personal approach. We serve individuals and businesses, with particular experience in small and medium-sized enterprises, technology companies, professional services and international organisations operating in Cyprus.
Our aim is not simply to sell a policy or compete on price, but to understand what the client is building and wants to protect.
As we mark ten years in business, we believe our position in the market is defined above all by the trust and long-term relationships we have built.
How are technology and digitalisation affecting the role of the insurance intermediary and their relationship with the client?
Technology is transforming every stage of the insurance process, from the initial assessment and information gathering to policy administration, renewals and claims. It enables faster communication, more accurate information and a simpler experience for the client.
However, digitalisation should not make insurance impersonal. Used properly, it reduces bureaucracy and allows advisers to devote more time to understanding the client, explaining complex terms and identifying gaps in cover.
At HJS Insurance, we see technology as a tool for strengthening personal relationships, rather than replacing them. Clients should receive prompt service while knowing that there is someone who understands their needs and will be there to support them, particularly when something unexpected happens.
What are the most pressing insurance needs facing businesses in Cyprus today?
Many businesses still treat insurance as a routine obligation or an annual purchase, rather than as part of their overall risk management. As a result, they may hold several policies yet remain exposed to risks that could cause serious financial loss or operational disruption.
Cyber risk is a clear example. An incident can lead to business interruption, data loss, liability to third parties, administrative fines, other repercussions and damage to a company’s reputation.
Significant gaps also exist in professional indemnity cover, directors’ and officers’ liability, cover for loss of profits and protection for key personnel. Meanwhile, group health insurance, life insurance and retirement benefits are becoming more important in attracting and retaining staff. The fundamental need, therefore, is for a structured risk assessment aligned with each business’s operations and objectives.
Can a modern insurance adviser take a preventive approach, rather than simply act as a “salesperson” for an insurance product?
Certainly. I believe that is how the role of a modern insurance adviser should now be defined. The conversation should not begin with “Which policy do you want?” but with “What could prevent your business from operating or achieving its objectives?”
The adviser needs to understand the client’s business model, contracts, people, assets and future plans. They can then identify risks, explain what can be insured, highlight exclusions and recommend appropriate limits of cover.
The value of this relationship becomes particularly clear when handling a claim. A good adviser helps the client understand the process, gather the necessary information and communicate effectively with the insurer. Insurance works best when considered proactively, rather than after a problem has already arisen.
Cyber risks, climate change, geopolitical developments and new forms of business activity are constantly creating new demands. How prepared is the Cypriot insurance market to respond to these emerging risks?
The Cypriot market is evolving and now offers more solutions for cyber risks, professional indemnity, directors’ and officers’ liability and complex international operations. At the same time, collaboration with international insurance markets is expanding access to specialist cover.
However, new risks are evolving faster than traditional products and assessment models. Artificial intelligence, digital assets, international supply chains and extreme weather events create exposures that do not always fit easily into conventional categories.
The challenge is not only to develop new products, but also to improve awareness, data quality and specialist advice. Insurance is part of a business’s resilience, alongside cybersecurity, contract management and business continuity planning.
In a market with many insurance options available, what should a client look for in an insurance adviser beyond a competitive price?
Price matters, but it should not be considered in isolation. A cheap policy has limited value if it does not address the client’s main risks, contains inappropriate exclusions or is based on incomplete information.
Clients should consider whether the adviser takes time to understand them, explains both the benefits and the limitations of the cover, and assesses options on criteria beyond the premium. Being accessible and providing long-term support are equally important, particularly when needs change or a claim arises.
Every client has different priorities. A technology company does not face the same risks as a property owner or a family. A good adviser listens first and makes recommendations afterwards, with knowledge, transparency, consistency and a real interest in the client’s needs.
Looking ahead, which trends do you believe will shape the insurance market in Cyprus, and what is HJS Insurance’s strategy for remaining a modern, reliable partner for individuals and businesses?
Digitalisation, artificial intelligence and the use of data will continue to change how insurance products are designed, distributed and serviced. Clients will expect simpler processes, faster decisions and more personalised communication. At the same time, cyber risks, climate change, regulatory developments and geopolitical uncertainty will increase the need for specialist expertise.
Insurance will also become more closely linked to prevention, helping clients understand and reduce risks before a loss occurs.
HJS Insurance’s strategy rests on three pillars: specialist expertise, technology and personal contact. We invest in tools that improve efficiency and communication while strengthening our expertise in business insurance, professional indemnity, cyber risks and group benefits.
As we enter our second decade, we remain committed to a clear goal: to understand what truly matters to each client and support them with honest, personalised and reliable advice.
Contact details
Website: www.hjsinsurance.com.cy
Tel.: 70005507
Office: Labs Tower, Nicosia

